Harbor at dawn

Here for our Florida neighbors

Trusted counsel dedicated to getting you back home.

If Hurricane Isaias took a piece of your roof, your fence, or your peace of mind, you don't have to sort out the insurance part alone. We help Florida property owners get their houses rebuilt — and we handle it in plain language, one clear step at a time.

Hurricane & Property
Personal Injury
Medical Malpractice
Trusts & Estates
We Help Homes Get Rebuilt✦Free Help After the Storm✦No Fee Unless We Recover✦Available 24 / 7✦English & Español
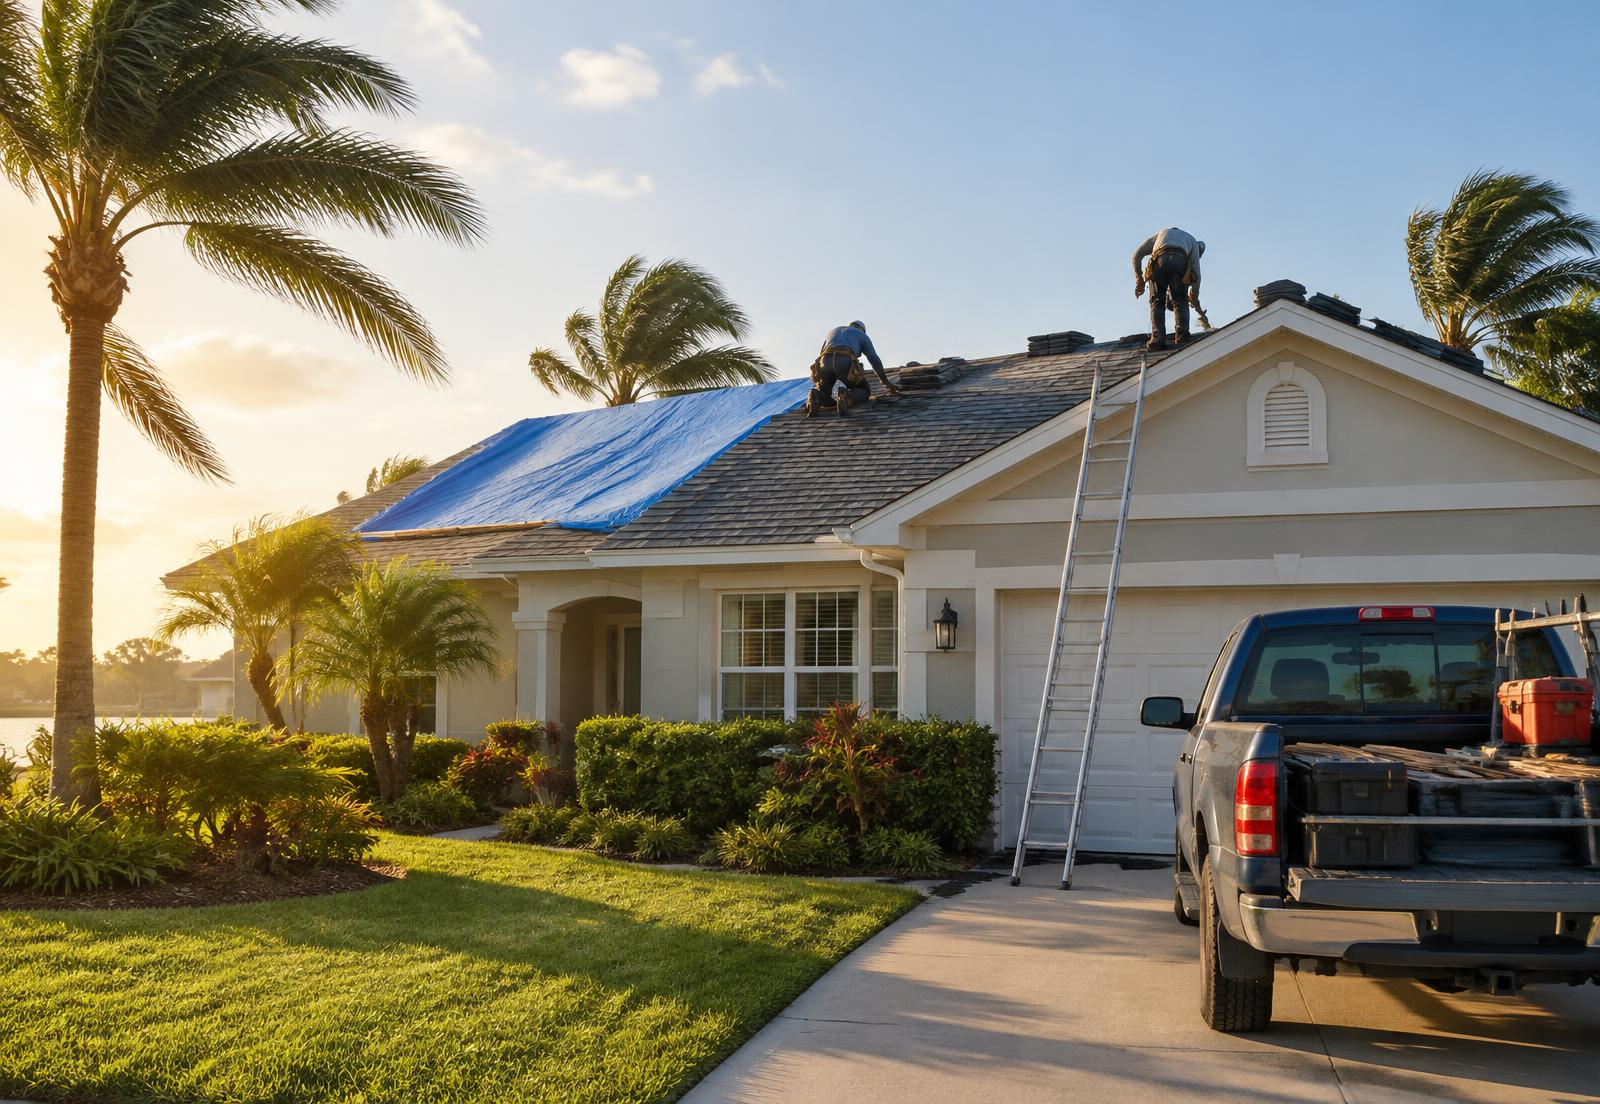
Workers repairing a Florida home's roof in the morning sun after a hurricane

Hurricane Isaias & Florida homes

We help hurricane property owners get their houses rebuilt.

Isaias came ashore near Destin on October 9, 2026 as a Category 2, and the damage varied street by street. Some homes barely flinched; others have a tarp where the roof used to be. Whatever your house looks like today, the goal is the same: get it properly paid for and properly rebuilt.

Ask about my home

Reading your policy with you

We pull up your declarations page, explain what you actually bought, and tell you what your carrier owes in plain words.

Making the estimate fair

We compare the carrier's number against your contractor's, line by line, and document what was left out.

Checking the deductible

Hurricane deductibles work differently from ordinary ones. We confirm which amount applies before you're charged.

Finding the hidden damage

Moisture in the walls, mold behind the drywall, roof layers that only show up weeks later — we get them into the claim.

Condos, HOAs & rentals

Roofs, common areas, assessments, and units where the association's policy and yours need to line up.

Keeping the work moving

Dates, adjusters, and promises are tracked in writing, so your repair doesn't sit in someone's inbox.

How we work a claim

Four steps, one finished roof.

01

Document

Photos, moisture readings, and a contractor's scope captured while everything is fresh — the single biggest thing you can do.

02

Explain

A plain-language read of your coverage, your deductible, and what a reasonable number looks like for your home.

03

Push

We answer each objection in writing and keep the claim moving — appraisal, mediation, or court if the carrier needs the push.

04

Rebuild

The finish line isn't a check. It's a new roof, a dry house, and your family back home in it.

Free help — no obligation

Your first two weeks
after Isaias.

A practical checklist for Florida homeowners, landlords, and association boards. Work down the list at your own pace — and share it with a neighbor who's still standing in a wet kitchen.

1

Photograph before you clean up

Every room, the roofline, the yard, the fence — before tarps, before haulers, before anyone hoses it off. Photos are the strongest thing you own.

2

Make it safe and keep the receipts

Tarps, plywood, fans, dehumidifiers, and a hotel night are usually recoverable. Save every invoice and log who came out and when.

3

Report the claim, write down the details

Note the claim number, the adjuster's name, and the date you gave notice. One page of notes saves weeks of guessing.

4

Get your own contractor estimate first

Walk your own property with a licensed contractor before you meet the carrier's adjuster. You'll compare two numbers instead of one.

5

Don't sign anything unread

A release, a full assignment, or a 'final' payment offer can close your claim early. Bring it to us and we'll read it with you — free.

6

Ask a neighbor to check theirs

A covered loss often looks like a small one from the ground. If a neighbor gave up on a low number, introduce them — the first call costs nothing.

The dates that matter

Knowing your dates keeps your options open.

Bring your policy and we'll confirm exactly what applies to your home — every policy reads a little differently.

Reporting the loss

Florida law generally gives one year from the date of loss to give notice of a hurricane claim — for Isaias, the date of loss is the October 9, 2026 landfall. Report it now; don't wait for the repair.

Damage found later

Supplemental claims — the leak you spot next spring — are generally open for eighteen months from that same date of loss.

The carrier's clock

Once you give notice, an insurer generally has sixty days to pay or deny, with limited exceptions. Silence is not a good sign — it's a reason to ask in writing.

Your deductible

Florida's hurricane deductible applies once per calendar year, and the hurricane period runs from the National Hurricane Center warning until 72 hours after the last watch or warning ends.

— 01

Hurricane & Property Rebuilding

We help homeowners, landlords, and associations get the insurance money that turns storm damage back into a finished house — and we carry the claim paperwork so you can focus on the repairs.

  • Roof, wind & water-intrusion losses
  • Low or incomplete estimates
  • Claims closed too early
— 02

Personal Injury

When negligence upends a life, we pursue full and fair recovery — from medical costs and lost wages to the quieter losses that don't fit on a spreadsheet.

  • Auto & trucking collisions
  • Premises liability
  • Product liability
— 03

Medical Malpractice

A second opinion when the first one cost you. We work with leading clinical experts to investigate harm, hold providers accountable, and recover what was lost.

  • Surgical & diagnostic errors
  • Birth injury
  • Wrongful death
— 04

Trusts & Estates

Plans that protect what you've built and the people you love — drafted in plain language, reviewed as your life changes, and ready when families need them most.

  • Wills & revocable trusts
  • Probate & administration
  • Estate planning
— 05

Real Estate

Closings, disputes, and everything in between — including homes caught mid-storm: damaged properties in active transactions, escrow disputes, and sellers who won't fix or credit.

  • Residential closings
  • Commercial transactions
  • Complex real estate litigation

The Approach

Three steps. No surprises.

01

Listen

We start with a free, unhurried conversation — by phone, video, or in person. No intake form before a human.

02

Assess

We review the facts honestly, explain your options in plain language, and tell you what we'd do if it were our family.

03

Represent

If we're a fit, we get to work — with clear communication and the standard we'd want for ourselves.

Good questions

After the storm. Before the paperwork.

Short, honest answers to what callers ask most. If yours isn't here, ask it — the first call is free.

My insurer says the damage wasn't from the storm. Is that the end of it?+

Not at all. A carrier's first answer is an opinion about cause, and opinions can be checked with an independent inspection, moisture readings, and a proper scope of repairs. Many homeowners we meet have a covered loss that simply wasn't documented yet.

The estimate is far below my contractor's. What should I do?+

Get both estimates in writing and compare them line by line. We price what was left out, document the missing items, and send the carrier a scope it can't wave off. Most low numbers move once they're answered item by item.

How long do I have to report Hurricane Isaias damage?+

Report it as soon as you can. Florida law generally gives one year from the date of loss to give notice — for Isaias, the date of loss is the October 9, 2026 landfall — and damage found later is generally claimable for eighteen months from that same date. Bring your policy and we'll confirm exactly what applies to you.

Do I have to pay a hurricane deductible before repairs start?+

Usually yes, and it's worth checking which deductible applies. Florida's hurricane deductible applies once per calendar year, and the hurricane period runs from the National Hurricane Center warning until 72 hours after the last watch or warning ends. We check your declarations page so you're not charged the wrong amount.

What does this cost?+

The first conversation is free and confidential. Injury cases are handled with no fee unless we recover. Property and insurance disputes are explained up front — hourly, capped, or fee-shifting where Florida law allows — before you sign anything.

Voices

What clients say when the work is done.

"The apartment above mine leaked into my kitchen. Michael fought their insurance company to get us a brand new kitchen and flooring!"
Barbara P — Property Damage Client
"We settled with a major hospital system in under 4 months for exactly what we demanded. They are the best!"
Carol C. — Medical Malpractice Client
"I am so happy with Harbor America, they fought to get me policy limits when someone rear ended me"
Michael V — Personal Injury Client
"Someone hit my boat and Harbor America got me way more than I could have imagined!"
Brett N — Personal Injury Client

Free storm help

Tell us what
happened to your home.

The first conversation is free and confidential. If you have them, send the claim number and the carrier's last letter — a photo of the roofline helps too. We answer every message within one business day, most within a few hours.

Phone
(561) 450-9414
Office
One Harbor Plaza, Suite 1400
Miami, Florida

Submitting this form does not create an attorney–client relationship. Do not include confidential information until such a relationship is established in writing.